Serena’s power generation was severely impacted by a subtropical cyclone in Rio Grande do Sul, but the company assures that financial losses will be mitigated through insurance and reimbursements.
The third quarter of 2026 was marked by an atypical operational challenge for Serena.
The company recorded a 12.6% decline in its total energy generation volume, which reached 1,832.9 GWh during the period.
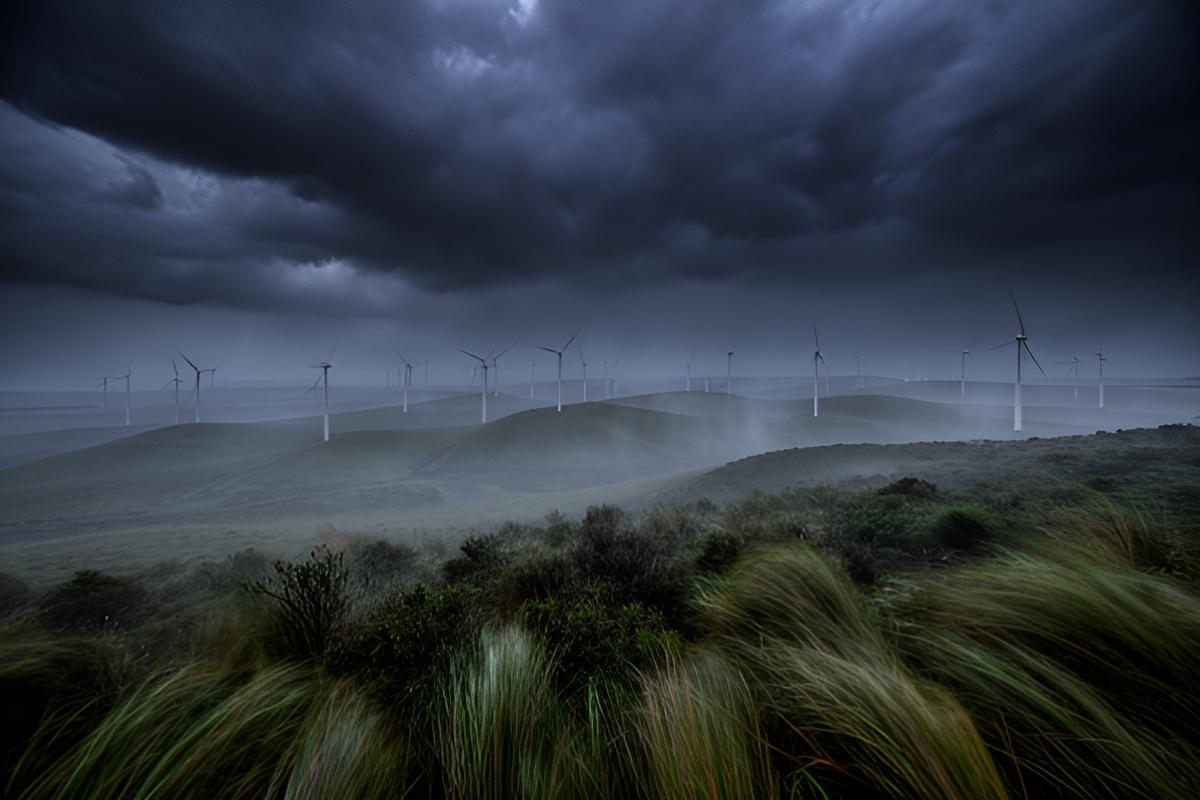
The main catalyst for this drop was the passage of a subtropical cyclone across the state of Rio Grande do Sul in August, a weather event that caused the loss of third‑party transmission lines and isolated the Chuí complex from the SIN.
Despite the logistical and operational setback, the company’s financial health showed resilience.
The organization’s adjusted net income jumped to R$ 231.8 million, a significant increase compared to the R$ 61.4 million recorded in the same period of 2025.
This result reinforces Serena’s ability to adapt in a climate‑volatile environment and amid challenges to electrical infrastructure.
Damage mitigation and recovery
The isolation of the Chuí complex resulted in a loss of approximately 531 GWh, a volume the company guarantees is fully eligible for reimbursement.
The company’s protection strategy includes activating the loss‑of‑profits coverage outlined in the Operational Risks policy, which should ensure financial stability during the full restoration of the network.
“The company does not expect a significant financial impact from the event, with the gradual resumption of operations projected to continue until February 2027.”
Asset performance diversity
While the wind sector faced obstacles in the South, other fronts delivered distinct results.
The Delta complex grew 4.2%, producing 794.7 GWh, and the Ventos da Bahia parks recorded a 4.4% increase.
Conversely, the Assuruá unit fell 9.8%.
Hydroelectric plants declined 20.1%, partially impacted by the divestment of assets such as Pipoca, completed in the first quarter of 2026.
Regarding profitability indicators, Serena’s adjusted EBITDA reached R$ 501.5 million—a 44% increase.
This performance was driven by a jump in energy gross profit and efficient management of operating costs.
Although net revenue showed a slight 2% decline, the 2% reduction in net debt, closing at R$ 5.315 billion, signals a more balanced balance sheet for the company’s upcoming strategic challenges.