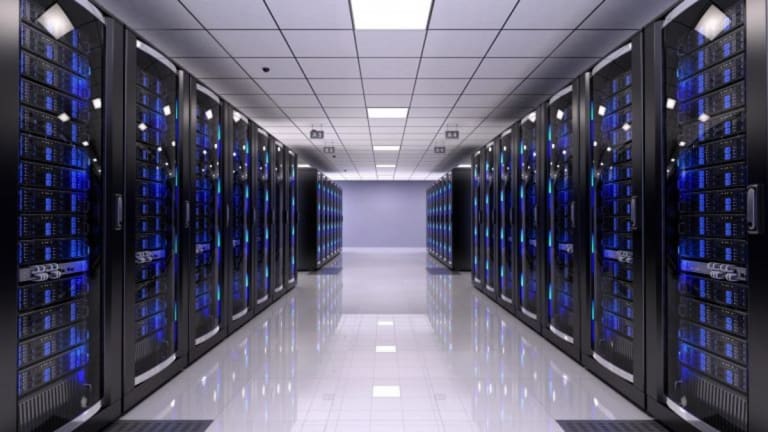
Brazil boosts technology and sustainability with new tax incentives for datacenters.
The Brazilian technology landscape gains a new chapter with the enactment of Law 15,504/26, which establishes the Special Taxation Regime for Datacenter Services (Redata). The initiative, led by President Luiz Inácio Lula da Silva, aims to attract investments and foster the development of crucial infrastructure for cloud computing and artificial intelligence in the country.
The new legislation marks a significant milestone for the sector, creating a more favorable environment for the installation and operation of datacenters. Its main appeal lies in the suspension of taxes on essential equipment and components, for both national and imported products, paving the way for exponential growth.
Redata: A New Pillar for Innovation
Redata, which originated from Bill 278/26, introduced by then-licensed congressman José Guimarães and approved with modifications by the Chamber of Deputies and the Federal Senate, covers a wide range of services.
It includes everything from data storage and processing to information management, with a special focus on cloud computing, high-performance processing, and the artificial intelligence ecosystem, encompassing model training and inference.
Criteria and Benefits for Companies
To qualify for the tax benefits, companies must maintain regularity with their federal tax obligations and have no outstanding issues with the Federal Public Sector Unpaid Credits Information Register (Cadin). It is important to note that companies opting for the Simples Nacional (a simplified tax regime) are not eligible for the program. The law also imposes clear requirements:
- Companies must meet sustainability criteria, ensuring that their entire electricity demand is supplied by renewable or low-emission sources.
- At least 10% of the effective supply of data processing, storage, and treatment must be allocated to the domestic market. Alternatively, this percentage can be directed to scientific, technological, and innovation institutions, or to public authorities.
- As another option, companies can reinvest 10% of the value of the benefited products into research, development, and innovation (R&D&I) projects.
Economic and Regional Impact
The tax suspension covers contributions such as PIS/Pasep, Cofins, and their import equivalents, in addition to IPI and Import Tax. Upon meeting the conditions, this suspension can be converted into a zero-rate tax, representing a significant cost reduction.
Beneficiary companies must make investments in Brazil equivalent to 2% of the value of products acquired under the regime, with a minimum of 40% of these investments directed towards digital economy projects and programs in the North, Northeast, and Central-West regions.
For datacenters located in these regions, supply and investment commitments are reduced by 20%.
Law 15,504/26, through Redata, signals a robust commitment to technological advancement and energy transition in Brazil.
By creating a favorable regulatory and fiscal environment, the country is positioned to attract significant investments in IT infrastructure, drive the adoption of emerging technologies, and strengthen its position in the global digital economy, all while encouraging more sustainable business practices.
RELATED NEWS
 Brazil Establishes National Critical Minerals Council, First Meeting Set for Planalto Palace
READ MORE
 Legal and Regulatory Transformations Place Legal Certainty at the Heart of the Electric Sector’s Agenda
READ MORE
 Lula Sanctions Critical Minerals Law, Securing R$5 Billion in Tax Incentives
READ MORE