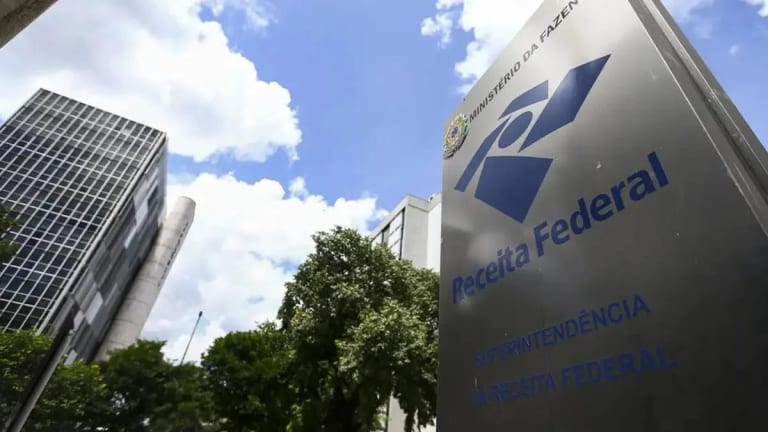
The Federal Revenue has blocked more than 270,000 applications to join the Simples Nacional tax regime for 2027. Companies have until the end of October to settle pending issues and avoid financial losses.
The Federal Revenue has released a report that raises a red flag for the Brazilian business sector. Out of nearly 470,000 entry applications analyzed for the Simples Nacional cycle, roughly 270,000 were immediately rejected. The measure directly impacts businesses seeking a simplified tax regime, which is essential for the financial health of micro and small enterprises.
The screening process revealed that only 199,161 applications were approved without caveats. The large volume of rejections reflects the existence of registration irregularities or pending debts, forcing taxpayers into a race against time to prevent exclusion from the regime from drastically altering their cost projections and pricing for the coming year.
Deadline and regularization implications
The tax authority has set October 30 as the deadline for organizations to correct the identified inconsistencies. Failing to regularize the situation within this schedule could result in an unexpected tax burden right at the beginning of 2027, impacting the competitiveness of thousands of businesses that rely on the regime’s reduced tax load.
This scenario unfolds simultaneously with a broader structural shift in the country. Alongside developments regarding Simples Nacional, the government recorded 854,000 registrations for the new IBS (Tax on Goods and Services) and CBS (Contribution on Goods and Services) regime, within the context of the Tax Reform.
Accounting experts point out:
“It is crucial that business owners urgently identify the exact cause of the rejection. Remaining in this simplified regime or not could be the turning point between profit and budget imbalance in corporate annual planning.”
The future of business and the impact on planning
The mass rejection serves as a reminder of the importance of continuous tax compliance. For the affected companies, the challenge now is to conduct a rapid internal audit to resolve debts or registration pending issues before the deadline closes.
The transition to the new tax model, combined with the strictness of the Federal Revenue, requires managers to pay close attention to official notices. Financial predictability for 2027 currently depends exclusively on the ability of these companies to resolve their pending issues by the end of this month, thereby ensuring the continuity of their activities under a more favorable taxation regime.